
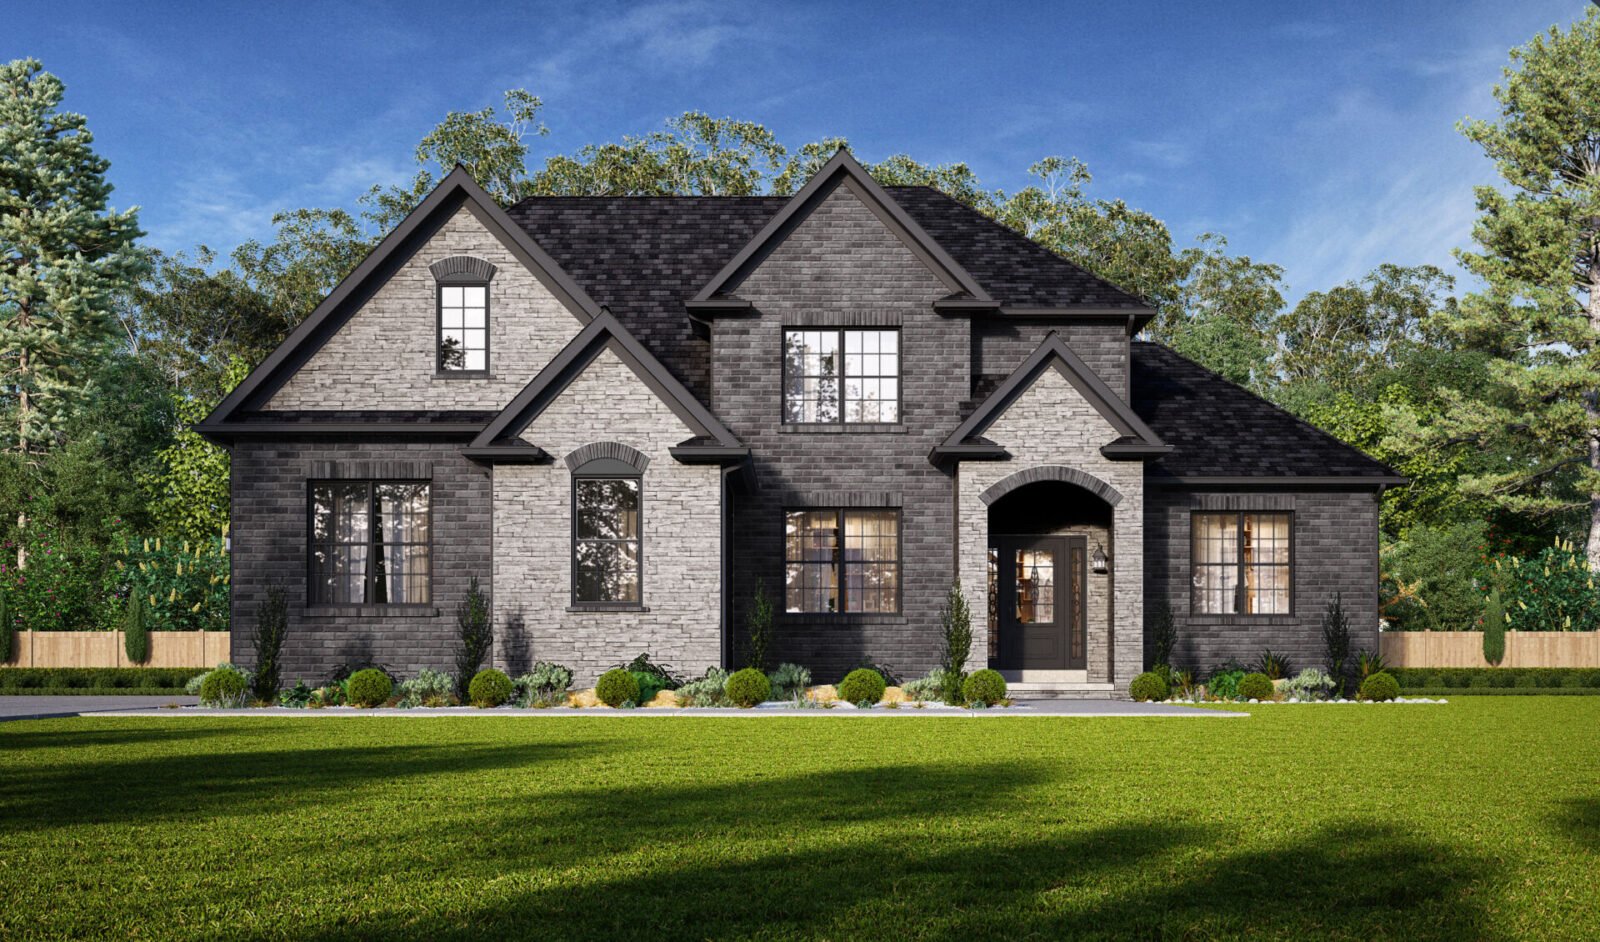
Embarking on the journey of designing and constructing a personalized residential property is an extraordinary milestone that gives you total freedom to create a space tailored to your exact lifestyle, preferences, and long-term goals. Rather than settling for the compromises, hidden wear-and-tear, or outdated layouts of pre-owned houses, constructing a home from the ground up ensures every square foot serves your household efficiently. However, before you can dive into architectural floor plans and interior finishes, you must master the foundational technicalities of land evaluation and financial engineering. Ensuring your chosen parcel can physically support construction requires a thorough investigation into how to know if your land is buildable.
Simultaneously, securing the right capital structure is paramount when navigating construction loans for custom homes. Unlike traditional mortgages used for buying existing resale houses, building a custom residence requires specialized financing that adapts to project phases, builder draws, and material milestones. Understanding these dual aspects of land feasibility and loan mechanics protects your investment from costly hurdles, prevents unexpected budget shortfalls, and lays the groundwork for a smooth, stress-free construction experience.
Part 1: Evaluating Land Suitability and Determining If Your Property Is Buildable
Before committing capital to purchase a vacant parcel or breaking ground on land you already own, performing a comprehensive feasibility assessment is non-negotiable. Not all land is created equal, and surface-level beauty can often mask severe subterranean or environmental challenges. A systematic site analysis ensures that your dream home can be constructed safely and economically without triggering unexpected engineering expenses.
1. Soil Composition and Geotechnical Testing
The earth beneath your proposed building site must possess adequate bearing capacity to securely support the immense weight of a multi-story residential structure. Geotechnical engineers conduct soil borings to analyze subsurface soil layers, compaction levels, and clay content. In Central Ohio, expansive clay soils are common, which can expand when wet and shrink during dry summer months. Identifying these characteristics early dictates whether standard foundation engineering will suffice or if specialized piers and modified footings are required.
2. Topography, Grading, and Stormwater Drainage
The physical lay of the land dictates both aesthetic design opportunities and structural protection requirements. Sloped lots offer stunning opportunities for walkout basements and dynamic architectural profiles, but they also demand sophisticated grading and stormwater management plans. Without proper drainage engineering, heavy seasonal rains can pool around your foundation, leading to hydrostatic pressure, basement leaks, and long-term structural degradation.
3. Utility Infrastructure and Access
Determining how your future home will connect construction loans for custom homes to essential services is a major factor in land buildability. Parcels located within urban or suburban subdivisions often feature stubbed-in municipal water, sanitary sewer, natural gas, and electrical lines at the property line. Conversely, rural acreage typically requires independent infrastructure assessments, including:
-
Private Well Drilling: Verifying the depth and sustainable yield of the local groundwater table.
-
Perc Testing: Conducting soil percolation tests to determine if the ground can support a functional septic system or if an engineered mound system is mandatory.
-
Electrical Grid Proximity: Calculating the cost of running utility transformers and overhead or underground lines from the nearest public road to your build site.
4. Environmental and Legal Encumbrances
A thorough title search and environmental survey will reveal whether your land is affected by protected wetlands, FEMA flood zones, mature tree preservation ordinances, or historical conservation easements. Building within or near these restricted areas is heavily regulated by local, state, and federal agencies, often requiring specialized environmental impact studies and costly mitigation permits.
Part 2: Demystifying Construction Loans for Custom Homes
Once you have confirmed that your land is physically buildable, you must align your vision with a sound financial strategy. Financing a custom build differs fundamentally from purchasing a pre-existing home because lenders are funding a property that does not yet fully exist.
1. How Construction-to-Permanent Loans Operate
The most popular financing vehicle for custom home builders is the construction-to-permanent loan (often called a single-close loan). This financial structure combines your land purchase or land payoff, construction financing, and final permanent mortgage into one streamlined closing process.
-
During Construction: Funds are disbursed in scheduled stages—known as “draws”—as specific building milestones are successfully completed and inspected (e.g., foundation pouring, framing completion, drywall installation). Throughout this phase, you typically make interest-only payments solely on the portion of the funds that have been drawn down.
-
Upon Completion: Once the final municipal occupancy permit is issued, your construction loan automatically transitions into a traditional permanent mortgage (such as a 15-year or 30-year fixed-rate loan), eliminating the need and expense of a second closing.
2. Managing Builder Draws and Contingency Funds
Lenders enforce strict oversight during the building phase to protect their investment. Independent inspectors evaluate the job site before approving each scheduled draw request. Additionally, financial advisors and lenders heavily recommend establishing a contingency fund (typically 5% to 10% of total construction costs) to handle unexpected site adjustments, weather delays, or custom finish upgrades without stalling the project timeline.
Part 3: Strategic Phases of Site and Financial Preparation
Effective preparation within a modern custom home building framework relies on a structured, transparent progression that accounts for both physical land constraints and financial realities:
-
Discovery and Preliminary Feasibility: Before signing a land purchase agreement or drawing a single architectural line, commission a professional land surveyor and consult with a construction lender to pre-qualify your budget parameters.
-
Design-Build and Loan Alignment: Collaborate with an experienced builder who understands local municipal guidelines and works seamlessly with construction lenders. They can provide detailed line-item specifications required by lending institutions for loan underwriting.
-
Permit Acquisition and Closing: Submit comprehensive architectural blueprints, engineering reports, and builder contracts to both your local building department and your lender to secure final loan approval and construction permits before breaking ground.
Crafting Sustainable and Future-Proof Interiors
While exterior site planning and financial loan structuring secure your legal and structural foundation, designing the interior framework of your custom home offers a unique opportunity to prioritize both elegance and everyday functionality. Contemporary architectural trends emphasize open-concept living spaces that seamlessly connect kitchens, dining areas, and family gathering spots, fostering an environment ideal for both entertaining and daily family interaction. Incorporating versatile bonus rooms that can transition from a home office to a guest suite or creative studio ensures your home adapts as your household grows.
Investing in smart home technology, LED lighting infrastructure, and advanced indoor air filtration further enhances your daily living experience. These upgrades not only elevate comfort but also protect your property’s long-term resale equity in a competitive real estate market.
Frequently Asked Questions
What is the typical timeframe for designing and building a custom home?
The entire process generally spans between 9 to 15 months from the initial architectural consultation to the final occupancy permit, depending on design complexity, engineering requirements, soil testing phases, and municipal review speeds.
How does a construction-to-permanent loan function during the build?
This financing structure provides funds in scheduled draws as construction milestones are met. You pay interest only on the drawn balance during building, which automatically rolls into a standard mortgage once approved.
Can I buy raw land with a construction loan?
Yes, many construction-to-permanent loans allow you to bundle the acquisition cost of the vacant land directly into your total loan amount, meaning you finance the land purchase and the home construction under a single closing.
How do I know if my land requires a well and septic system?
If municipal water and sanitary sewer connections are not available at the street boundary of your parcel, your builder will coordinate soil percolation tests for septic design and exploratory drilling to establish a private well.
Are custom homes more expensive to insure than resale houses?
Insurance premiums are based on total replacement cost rather than market value. Because custom finishes represent higher rebuilding costs, premiums can be slightly higher, though modern safety and fire-resistant materials often qualify owners for policy discounts.