
What Services Should You Expect From a Trusted Small Business Lender?
AI OverviewA trusted small business lender provides more than capital access. These professionals assess financial records, study business operations, review repayment capacity, and guide companies toward suitable lending structures. Their services often include application reviews, funding analysis, financial guidance, and ongoing support for businesses managing growth expenses. |
Introduction
Construction businesses often face a difficult financial gap between project expenses and incoming payments. Material purchases, equipment costs, payroll obligations, and subcontractor payments may arrive before customer invoices are completed. This timing issue can place pressure on otherwise healthy operations.
The challenge becomes greater when business owners seek funding without understanding lender requirements. Incomplete financial records, unclear project budgets, and weak cash flow planning may slow approval processes or limit available options. Many companies lose valuable opportunities because their financial preparation does not match lending standards.
A trusted small business lender helps bridge this gap by reviewing business conditions, studying financial details, and identifying suitable funding paths. Understanding these services gives construction professionals a clearer view of the lending process and the support they should expect.
Financial Review Standards For Business Lending
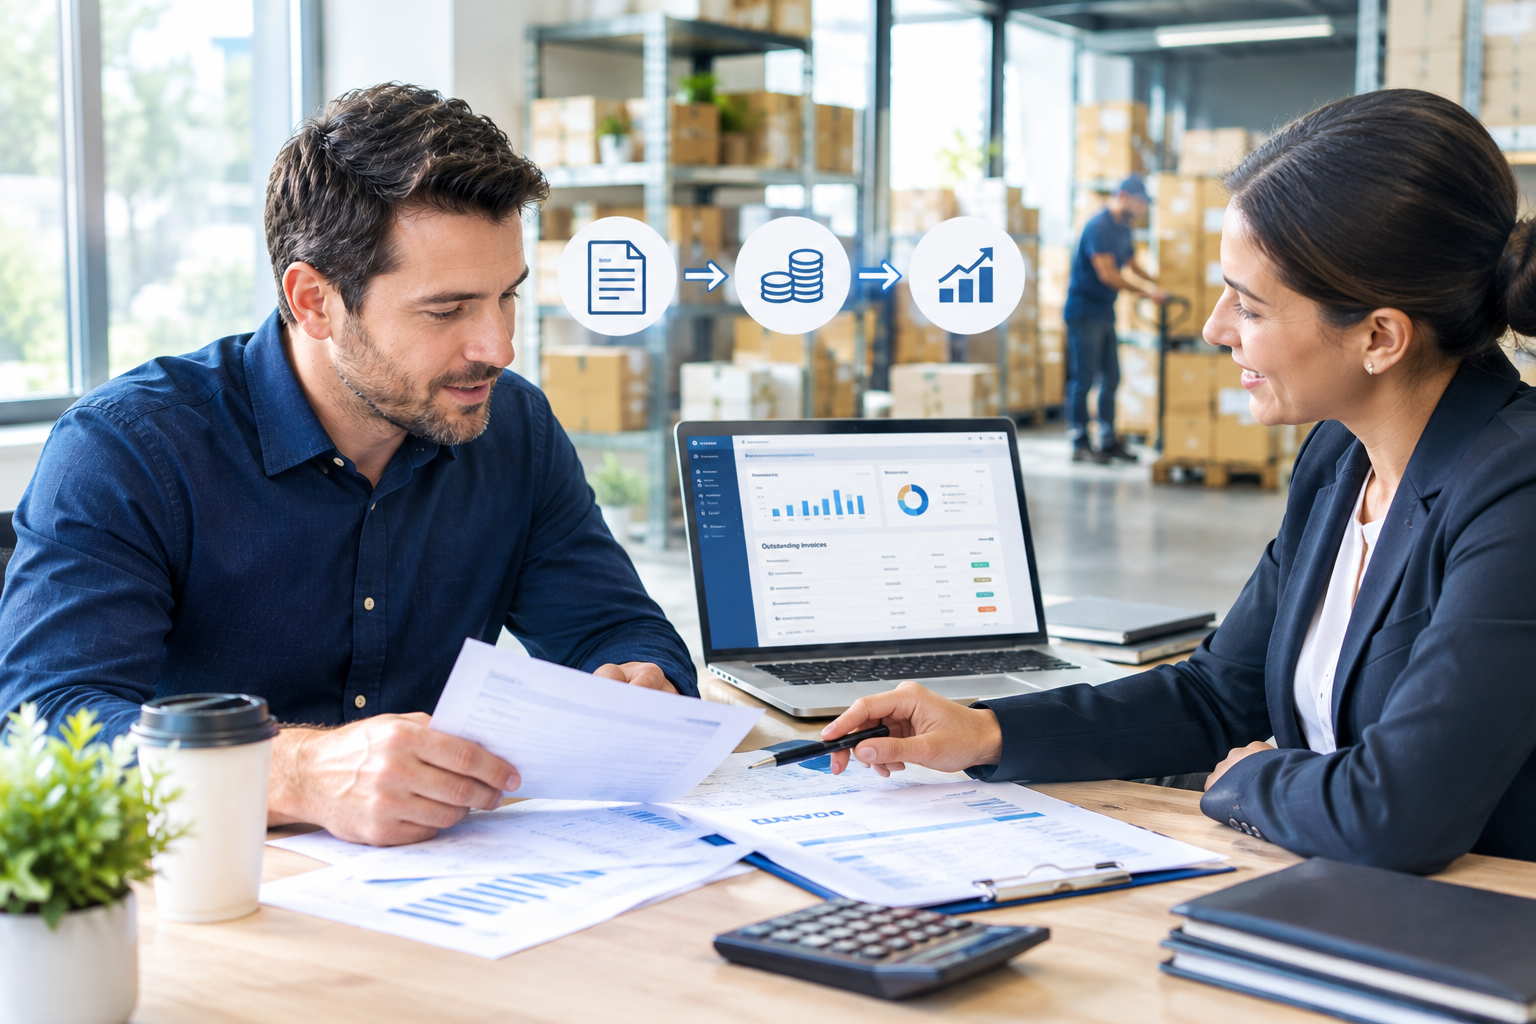
A trusted small business lender begins with a detailed review of a company’s financial position rather than focusing only on revenue figures. This review commonly includes income statements, bank activity, tax documents, debt obligations, project contracts, and operational costs. For construction firms, lenders often examine job schedules, payment cycles, equipment expenses, and seasonal changes that influence cash availability.
The purpose is to understand the full business picture before discussing funding options. A professional lending review considers both current conditions and future obligations. This approach allows business owners to evaluate funding choices based on actual operating needs instead of short-term pressure.
Capital Assessment Practices Across Growth Sectors
A strong funding assessment requires more than checking a credit score. A trusted small business lender studies several factors that show financial stability and repayment ability.
Construction companies usually operate with unique financial patterns. Large projects may require significant upfront spending before payments arrive. Because of this, lenders review contract values, outstanding invoices, supplier terms, and project timelines.
Business Records Review Standards
Accurate records help create a clear financial picture. Businesses seeking capital should maintain organized documents that show:
- Recent revenue history
- Current business expenses
- Existing loan responsibilities
- Equipment ownership details
- Active project information
Clear documentation allows lenders to understand operational performance and identify suitable funding structures. It also helps business owners recognize areas that may need attention before submitting an application.
Funding Structure Evaluation Methods
Different companies require different forms of capital support. Some may need equipment financing, while others may need working capital for project completion. A trusted small business lender reviews the purpose of funds, repayment ability, and business goals before suggesting available options.
This process helps companies avoid choosing financing based only on speed. Instead, funding decisions become connected to business conditions, project requirements, and financial planning.
Funding Evaluation Points For Construction Firms
Construction funding decisions depend on several operational details. A trusted small business lender typically reviews project schedules, contract strength, revenue consistency, and existing financial commitments. These factors help determine whether a company can manage additional repayment responsibilities while maintaining daily operations.
Key evaluation areas often include:
- Annual business revenue and cash movement
- Credit history and payment records
- Length of time operating in the industry
- Current project commitments
- Planned use of borrowed funds
These details provide a clearer view of financial readiness. A company with organized records and realistic budgets may present a stronger lending profile. The goal is not only obtaining capital but selecting an option that fits business capacity.
Small business funding solutions can support construction companies facing equipment purchases, expansion plans, payroll needs, and project-related expenses. However, the right structure depends on careful review of financial circumstances and operational goals.
Lending Metrics Used In Approval Decisions
Financial metrics play a major role in lending analysis. A trusted small business lender may examine debt service coverage, revenue trends, credit history, account activity, and expense patterns before reaching a decision.
For construction businesses, cash flow timing is especially important. A company may show strong yearly revenue but still experience pressure during periods when project payments are delayed. Lenders often review whether incoming funds can support existing obligations and new repayment schedules.
Approval reviews may also consider industry experience and business consistency. Companies with stable operations, documented projects, and clear financial records generally provide more information for evaluation. According to common lending practices, many small businesses are assessed using a combination of financial history, business performance, and repayment capability rather than a single measurement.
Operational Support Beyond Basic Financing
Funding services often include guidance that helps business owners understand available choices. A trusted small business lender may explain loan structures, repayment terms, document requirements, and application expectations throughout the process.
For construction professionals, this support can be useful when managing complex financial decisions.
- Reviewing funding purposes before applying
- Understanding payment schedules
- Comparing different financing structures
- Preparing necessary financial documents
- Planning around future business expenses
Small business funding solutions are most effective when they match the company’s operating model. A contractor managing several active projects may have different needs compared with a company purchasing equipment for future growth.
A professional lender focuses on reviewing business information carefully and helping owners make informed decisions based on their financial position.
Strategic Planning Factors Before Loan Requests
Before requesting capital, construction companies should examine their internal financial systems. A trusted small business lender often reviews whether a business has clear records, realistic budgets, and organized project information.
Preparation Areas For Construction Owners
Strong preparation can improve the lending discussion. Business owners should review:
- Current project costs
- Expected payment dates
- Equipment requirements
- Monthly operating expenses
- Existing financial commitments
Small business funding solutions can become easier to evaluate when business owners understand their own financial requirements. Preparation allows lenders and companies to discuss funding needs with better information.
Planning before a request also reduces confusion during the review process. Companies that understand their financial position can select options that align with their operational demands.
Conclusion
Strong financial decisions begin before capital is requested. Construction companies that understand their numbers, project cycles, and future obligations create a clearer path toward funding discussions. A trusted small business lender provides value by reviewing these factors and helping businesses assess available choices. Much like professionals who work with Simply Capital Source as an industry resource, business owners can benefit from guidance that focuses on financial readiness and practical lending knowledge. The right approach to small business funding solutions starts with preparation, accurate information, and a clear understanding of business needs.
Frequently Asked Questions (FAQs)
1. What services does a trusted small business lender provide?
A trusted small business lender reviews finances, evaluates funding needs, and explains suitable lending options.
2. Can small business funding solutions help construction companies?
Small business funding solutions can support equipment purchases, operating costs, and project-related expenses.
3. What documents are commonly reviewed during lending?
Lenders usually review revenue records, bank statements, tax documents, and business expense information.
4. Why do construction firms need financial planning before borrowing?
Financial planning helps companies understand repayment ability and select suitable funding structures.
5. How does a lender evaluate business stability?
A lender studies revenue patterns, credit history, expenses, and operational performance before making decisions.